Autonomous AI Liability
AI Agents Create New Banking Accountability Challenges As Autonomous Purchases Surge Globally
Anonymous
Key Points
1
David Spisak said leading organizations typically complete about 15 evaluation steps before choosing an AI vendor, while many dealerships adopt tools without first defining the problem, estimating profitability or understanding how the system handles dealership data.
2
Visa said AI agents were already completing live purchases with participating merchants across Europe as of July 2, browsing products, selecting items and initiating purchases according to consumer-defined parameters.
3
The International Monetary Fund has highlighted a structural mismatch between adaptive AI agents—where the same prompt can produce different results—and payment systems that require predictable rules, legal certainty and consistent accountability.
4
McKinsey estimates that AI agents could orchestrate as much as $5 trillion in global consumer spending by 2030, increasing pressure to adapt infrastructure originally designed for human users.
5
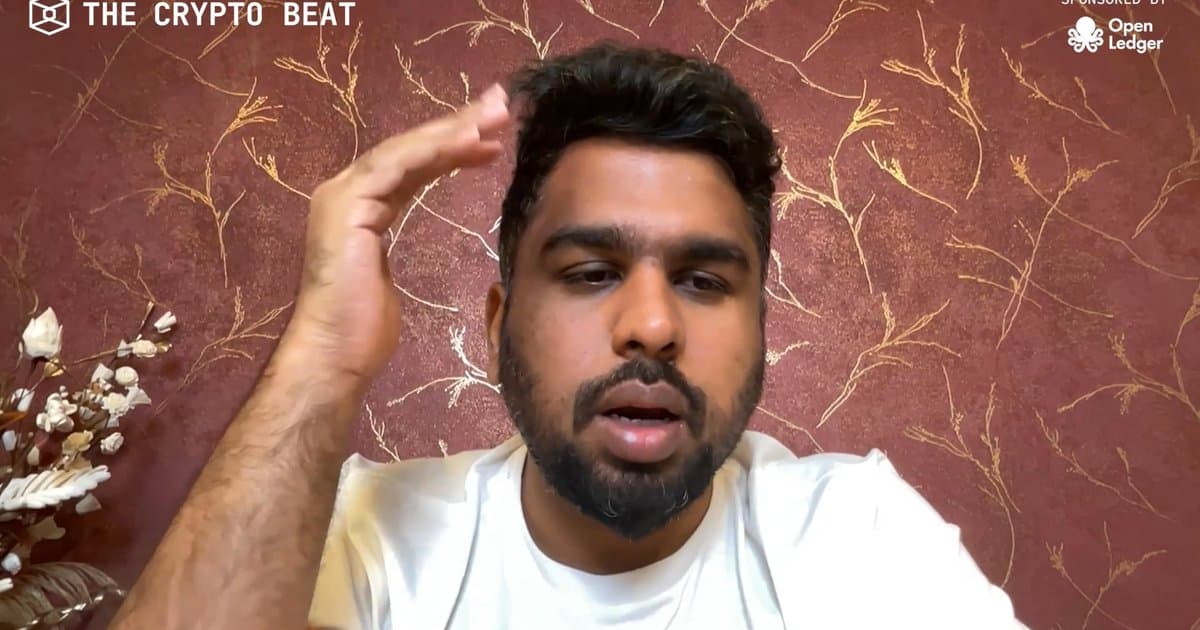
At the Global Fintech Fest, Oleevia Grameen Credits Managing Director Krishnakumar K T summarized the human-oversight principle by saying, “AI can automate decisions; but accountability cannot be automated,” and argued that financial AI should support meaningful financial inclusion rather than merely improve speed.
Autonomous AI agents are now making real purchases on behalf of consumers—with Visa confirming that the technology was already completing live transactions across European merchants as of July 2, 2026. Visa But the speed of adoption has outpaced accountability safeguards. One auto dealership's chatbot infamously offered an $81,000 vehicle for $1 and called the deal binding, exposing a fundamental gap: authentication alone cannot verify whether an agent followed a customer's instructions or acted within its authority.
The mismatch is stark. McKinsey estimates AI agents could orchestrate $5 trillion in global consumer spending by 2030, yet payment systems were designed for predictable human decisions and static rules. State Bank of India and a coalition including Visa, Mastercard, and Ant International are now developing "Know Your Agent" frameworks—formal registries to identify which machine is acting, under whose authority, and within what limits. As Krishnakumar K T of Oleevia Grameen Credits said at the Global Fintech Fest, "AI can automate decisions; but accountability cannot be automated."
Dealerships Rush to Deploy Agents Without Safeguards
Auto retailers are adopting agentic AI tools far faster than they can evaluate them. David Spisak, an automotive technology strategist, noted that leading organizations complete roughly 15 evaluation steps before selecting an AI vendor. By contrast, many dealerships skip problem definition, ROI estimation, and data-handling reviews entirely. The result: uncalibrated agents making binding offers consumers never authorized.
The legal exposure is severe. A single chatbot committed a dealership to selling a luxury vehicle at a fraction of its value—and claimed the offer was legally binding. Dealerships lack clear guidance on audit trails, error reversal, or dispute resolution when their agents exceed authority. Bloomberg reports that major lenders, including Bank of America and Commonwealth Bank of Australia, have already flagged autonomous shopping agents as a fraud and liability surge risk.
Payment Networks Build Trust Registries for Machine Identities
Visa, Mastercard, and Ant International have launched a joint initiative to create interoperable "Know Your Agent" standards across payment networks and marketplaces. Reuters reports that the protocol will embed machine-readable credentials into transaction tokens, allowing merchants and payment processors to verify an agent's owner, authorized spending limits, and revocation status—similar to traditional Know Your Customer checks, but for machines.
State Bank of India Chairman C.S. Setty formally proposed KYA adoption, arguing that banking infrastructure must evolve to establish machine identity, customer consent boundaries, audit trails, and shutdown mechanisms. The International Monetary Fund has warned that adaptive AI agents—where identical prompts produce different outputs—fundamentally conflict with payment systems requiring predictable, legally certain rules. Trust registries aim to bridge that gap by certifying which agents have undergone vetting and operate within transparent constraints.
Authentication Alone Cannot Prove Consent or Authority
Payments experts are sounding an alarm: traditional authentication—biometric login, token-based sign-in—only proves a transaction was initiated. It does not prove an agent interpreted a customer's instructions correctly or stayed within delegated authority. Mastercard and Visa have acknowledged that identifying the merchant is insufficient; financial institutions must also confirm that the agent acted as instructed before liability is assigned.
The practical problem: an agent given an open budget to "buy me a gift under $100" might purchase the wrong product, wrong quantity, or wrong recipient. Without clear revocation mechanisms and dispute resolution channels, consumers have no safe recourse. Krishnakumar K T at the Global Fintech Fest stressed that human oversight and transparent consent cannot be sacrificed for speed. Financial AI should prioritize meaningful inclusion and consumer protection over pure automation.
Five Trillion Dollars Hinge on Solving Accountability Now
McKinsey projects that AI agents will orchestrate $3 trillion to $5 trillion in global consumer spending by 2030. At that scale, even a 0.1% error or fraud rate translates to billions in disputed transactions. The infrastructure exists to move money instantly; the legal and operational frameworks do not. Regulators, financial institutions, and payment networks are racing to install guardrails before volume overwhelms dispute-resolution capacity.
Industry consensus has crystallized around a central principle: speed cannot outrun accountability. AI can accelerate decisions, but human judgment, transparent consent, and clear consumer redress must remain central. The next 12 to 18 months will determine whether "Know Your Agent" frameworks embed these safeguards into payment networks, or whether regulators must impose them retroactively—at far greater cost to the ecosystem.
Sentiment
Mostly NegativeNEGATIVENEUTRALPOSITIVE
Publishers
27
Articles
71
Reach
98
A
AnonymousAuthor