Canadian Energy Revival
Middle East Upheaval Revives Canadian Energy Investment Amid Global Supply Pressures
Anonymous
Key Points
1
The Alberta modeling projects that the proposed economic arrangement could increase oil-sands GDP by as much as $476 billion cumulatively over 25 years, while raising 2050 employment by up to 22,000 jobs and annual provincial royalties by up to $4 billion.
2
The renewed interest in Canadian energy reverses a decade-long pattern in which foreign companies partially or fully divested from Canada’s fossil-fuel sector; TotalEnergies, ConocoPhillips, Equinor and BP are reportedly reviewing potential Canadian acquisition targets, although sources cautioned that no additional deals are guaranteed.
3
BC Hydro CEO Charlotte Mitha said electricity demand is expected to rise about 20% by the end of the decade and roughly 50% by 2050, with proposed industrial projects requiring 300 to 600 megawatts each—up to half the capacity of the Site C dam.
4
Uncertainty over Hormuz oil flows has been worsened by a surge in “dark crossings,” in which tankers disable navigation and identification systems, as well as a U.S. request that commercial satellite companies delay Gulf imagery; analysts are therefore combining satellite images with port records, tanker drafts, loading schedules and refinery data.
5
The oil-stockpile comparison does not include the coordinated emergency release by International Energy Agency members in March 2026; China’s estimated 1.4 billion barrels nevertheless exceed the combined strategic inventories of the United States, Japan, OECD Europe, Saudi Arabia, South Korea, Iran, the United Arab Emirates and India.
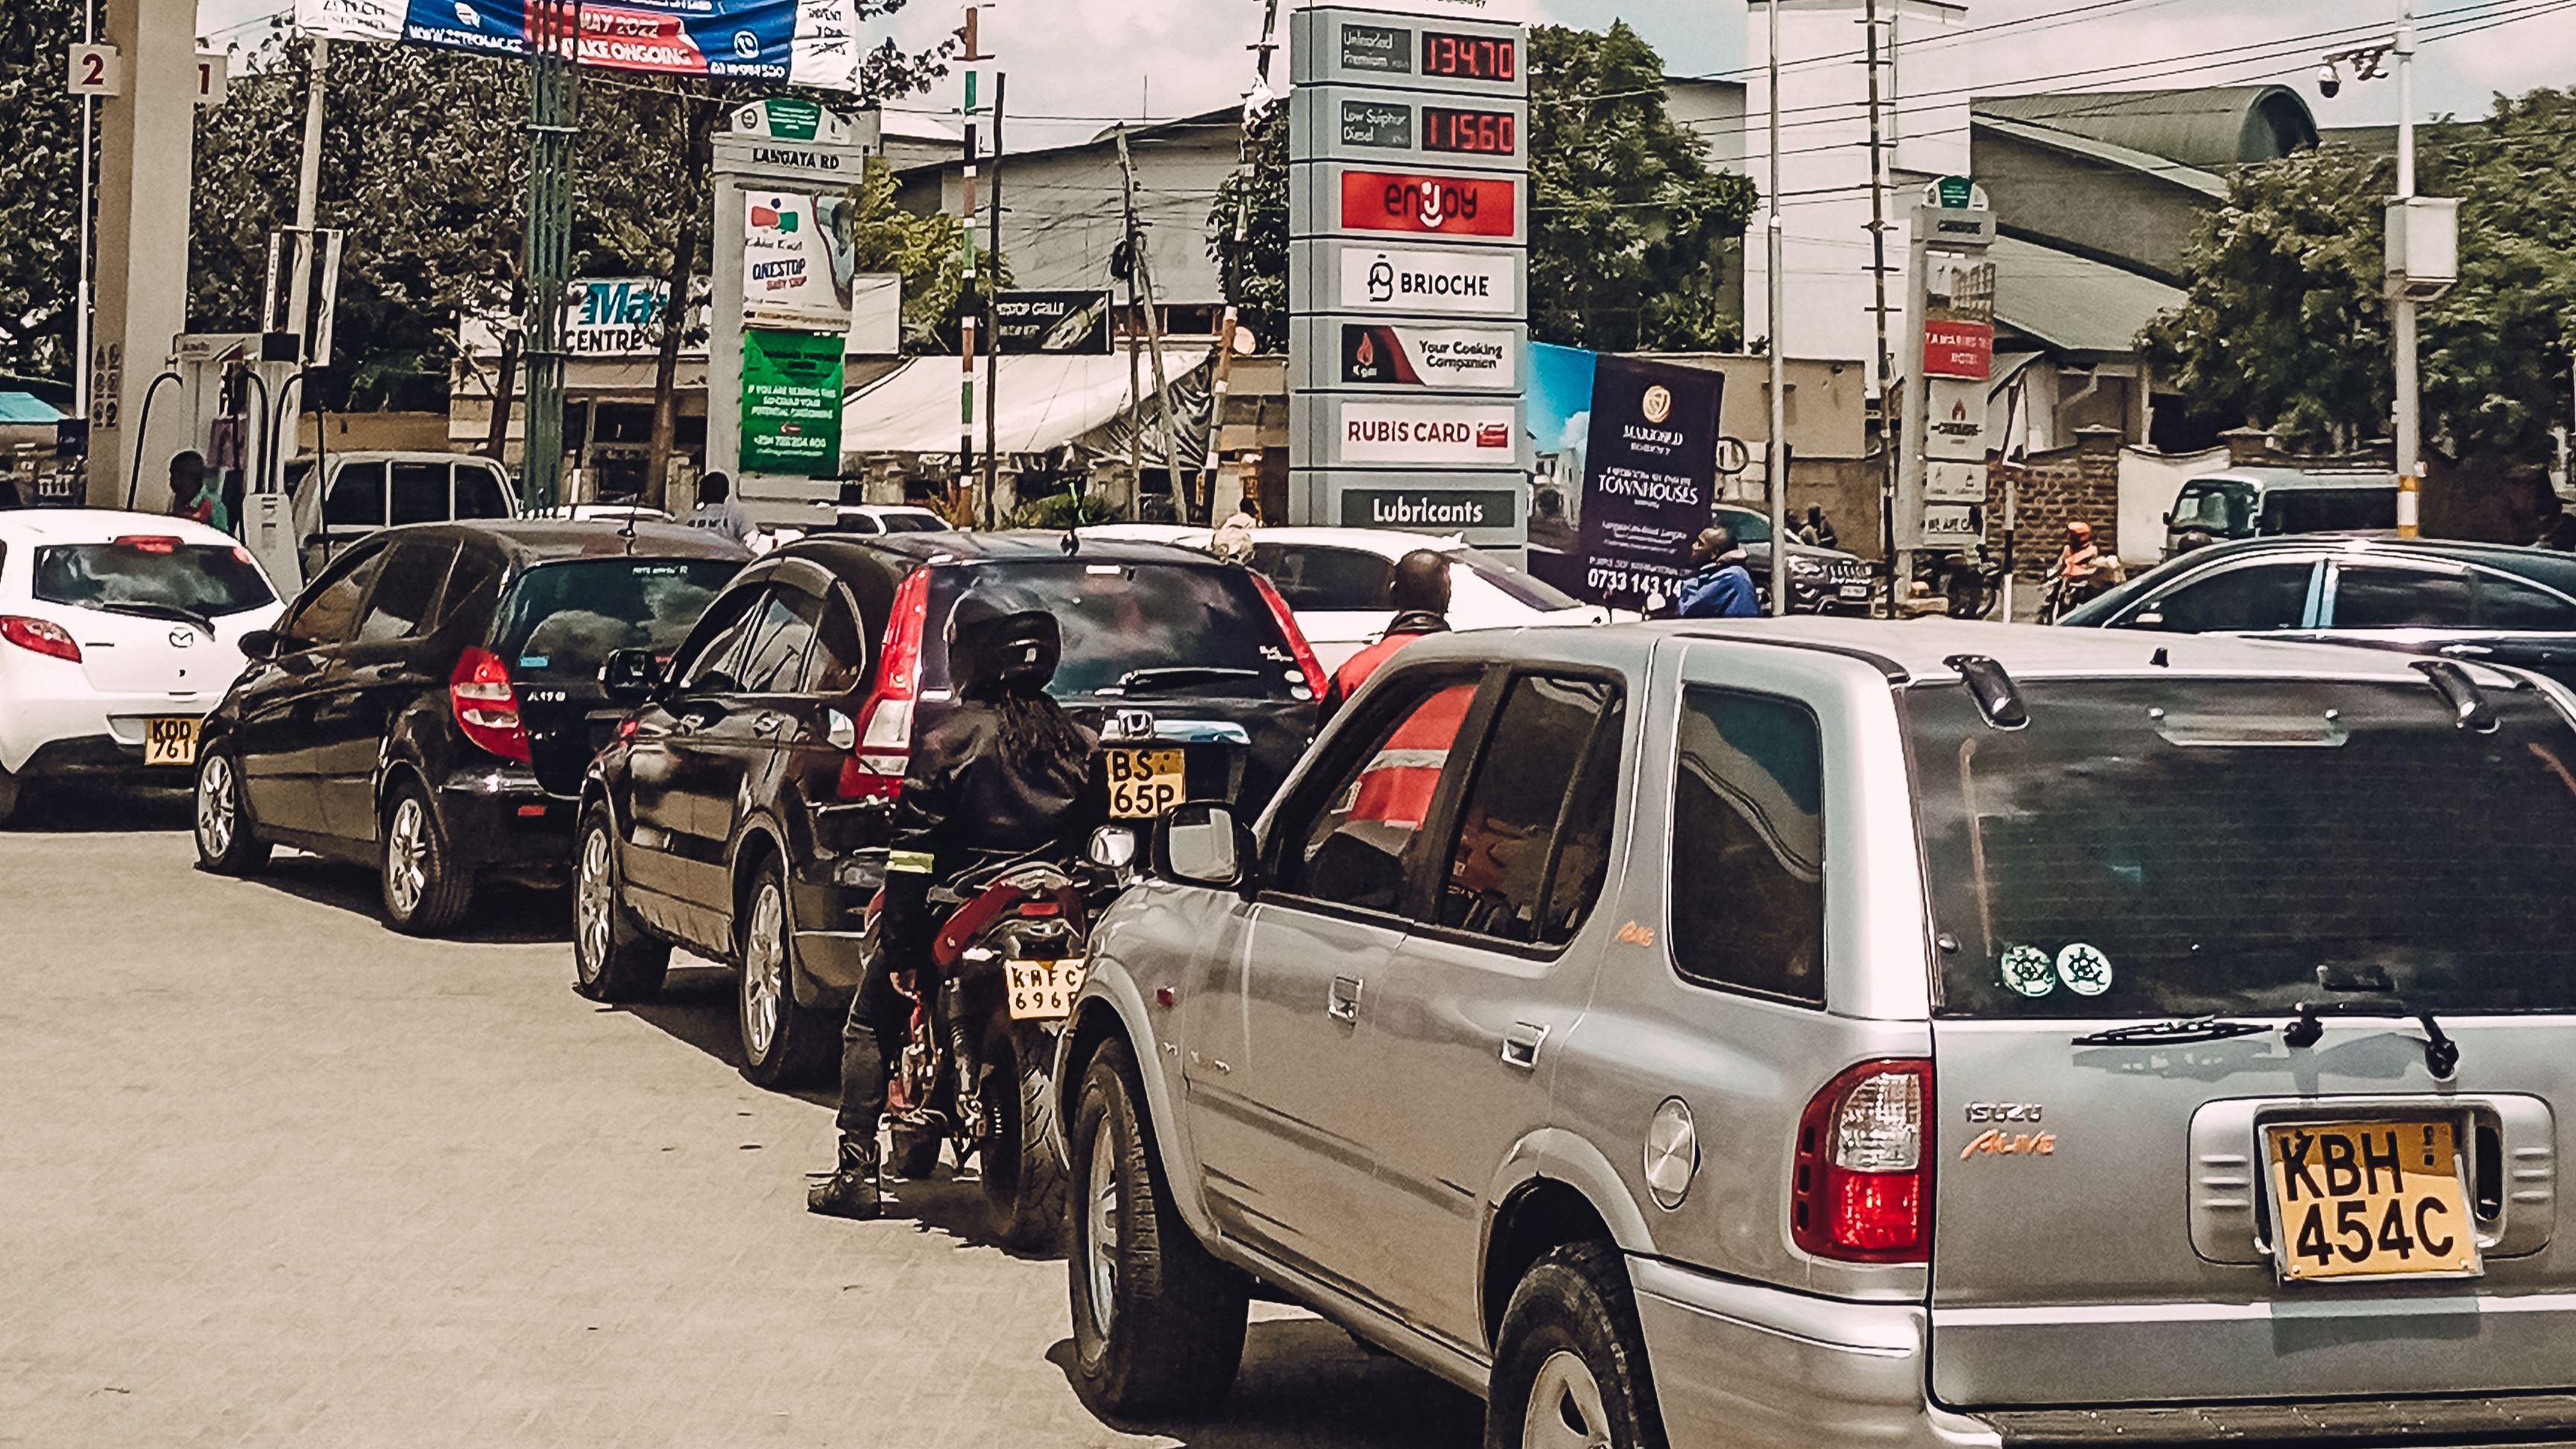
Middle East turmoil is luring global energy giants back to Canada after a decade of retreat. Shell announced a $16.4 billion deal to buy Canadian oil producer ARC Resources in late April 2026, signaling a dramatic shift as Brent crude crude oil climbed above $100 a barrel amid supply fears. The move reflects a hard truth: disruptions in the Strait of Hormuz have made Canada's stable, low-cost energy assets suddenly attractive again.
The turnaround is reshaping North America's energy landscape. EnergyNow reports that Canada's investment climate is shifting as geopolitical risks elevate the nation's appeal. Analysts say other majors—TotalEnergies, ConocoPhillips, Equinor, and BP—are now reviewing Canadian acquisition targets, reversing years of divestment. Meanwhile, modeling studies suggest a reformed economic framework could add $364 billion in oil-sands investment by 2050 and boost Alberta's annual royalties by up to $4 billion.
Shell Bets Big on Canadian Oil as Middle East Tensions Rise
Shell closed its $16.4 billion takeover of ARC Resources on April 27, 2026, in what analysts call a watershed moment for Canadian energy. Shell CEO Wael Sawan called ARC a "high-quality, low-cost and low-carbon producer," emphasizing that the deal secures long-term natural gas supplies for Shell's liquefied natural gas exports. The premium paid—27 percent above ARC's April close—underscores how badly global majors now want stable, North American energy sources.
ARC Resources CEO Terry Anderson stated the company would "realize tremendous value" and "deliver on Canada's exciting energy future" as part of Shell's global portfolio. The deal's speed and size mark a sharp reversal from 2016 to 2025, when TotalEnergies, ConocoPhillips, Equinor, and BP steadily exited Canadian assets. Now those same firms are quietly reviewing new acquisition targets, signaling that the calculus on Canadian risk has fundamentally shifted.
Hormuz Chaos Drives Brent Above $100 and Reshapes Risk Calculus
Brent crude has surged past $100 a barrel as uncertainty grips the Strait of Hormuz, the world's most vital oil chokepoint. Tankers are disabling navigation systems in what traders call "dark crossings," making it hard to track flows. The U.S. government has also asked commercial satellite firms to delay publishing Gulf imagery, further obscuring supply chains. Analysts are now fusing satellite radar, port records, vessel drafts, and refinery data just to estimate what oil actually moves through the region.
For energy majors, the message is clear: Middle East supply is too risky. Canadian oil and gas—produced under stable Western regulation with transparent permitting—now looks like a bargain. EnergyNow notes that Canada is being repositioned as a "secure and reliable energy" sanctuary in an age of disruption. The International Energy Agency coordinated an emergency stock release in March 2026 to calm markets, but the underlying threat remains. That's why Shell and its peers are writing checks for Canadian assets.
BC Hydro Extends Gas Plants to Feed Surging Data Center and Mining Demand
British Columbia is facing a power crunch that threatens to override climate ambitions. BC Hydro CEO Charlotte Mitha announced that electricity demand will jump about 20 percent by 2030 and roughly 50 percent by 2050. Single industrial projects—especially data centers and mining operations—now request 300 to 600 megawatts each, equivalent to half the output of the Site C dam. Hydro is extending the lives of natural-gas-fired plants to meet the gap.
The bind reveals a hard trade-off: British Columbia cannot electrify transport, heating, and data servers without far more electricity. Renewable capacity is being built, but not fast enough. That means gas-fired generation, which emits carbon, is becoming necessary to avoid blackouts. BC Hydro is reluctant to build new gas plants, but demand may force the issue. This dilemma mirrors global energy policy: decarbonization runs up against the reality of rising power needs.
China's Oil Stockpile Dwarfs Western Reserves, Shaping Global Leverage
China maintains a strategic petroleum reserve of an estimated 1.4 billion barrels—larger than the combined inventories of the United States, Japan, OECD Europe, Saudi Arabia, South Korea, Iran, the United Arab Emirates, and India put together. This massive buffer gives Beijing a cushion against Middle East supply shocks that Western economies simply do not possess. Even after the International Energy Agency coordinated an emergency stock release in March 2026, China's reserve advantage remains overwhelming.
The disparity is geopolitical leverage. Western energy consumers face tighter supplies and higher prices. China, by contrast, can tap its 1.4-billion-barrel reserve to stabilize domestic markets and negotiate better terms with producers. This asymmetry explains why Shell, TotalEnergies, and other majors are moving aggressively into Canadian energy. They need diversified, stable sources outside the Middle East and beyond Beijing's reach. Canada's role as an alternative supplier has never been more valuable.
Sentiment
Mostly NegativeNEGATIVENEUTRALPOSITIVE
Publishers
30
Articles
4
Reach
34
A
AnonymousAuthor


